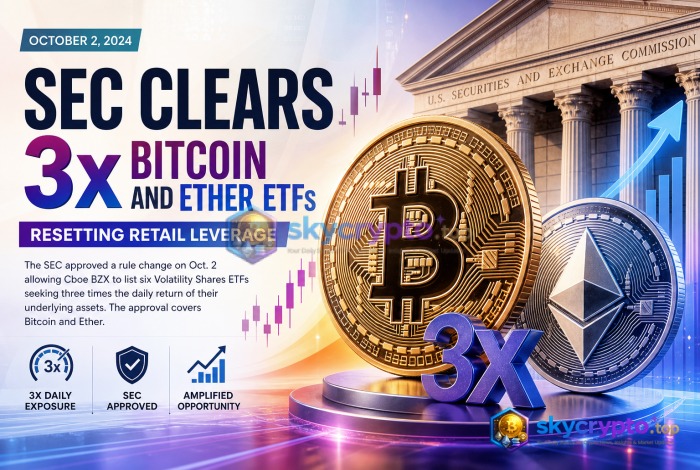
The U.S. Securities and Exchange Commission approved a rule change on Oct. 2 that allows Cboe BZX to list six Volatility Shares exchange-traded funds seeking three times the daily return of their underlying assets. The approval covers bitcoin and ether products, plus gold, silver, crude oil and natural gas, and marks the first time U.S. crypto ETFs can target more than two times daily exposure. The move hands traders a faster tool for catching sharp moves, while also introducing a product that can amplify volatility through daily rebalancing and decay.
- SEC approval opens the door to 3x daily bitcoin and ether ETFs, ending the prior 2x cap for U.S. crypto funds.
- The funds will use regulated futures, not spot tokens, and must rebalance daily to maintain their 3x target.
- Mechanical buying and selling can intensify intraday moves, while volatility decay can erode returns in choppy markets.
- Trading has not begun because the issuer still needs the SEC to declare its registration statement effective.
Market Reaction
Traders reacted quickly to the approval because the product changes the risk surface for short-term bitcoin and ether exposure. A 3x daily fund is not a passive holding; it is a tactical instrument designed for traders who want amplified moves without opening a futures account, posting margin, or managing rollover. The approval removes a regulatory ceiling that had limited U.S. crypto leverage to 2x daily exposure, which had kept many traders on perpetual swaps, options, or offshore venues. The shift is likely to pull some flow into regulated exchange-traded products, especially among investors who prefer fund-like access but still want aggressive directional exposure.
The immediate market effect is not simply a price bid. The more important reaction is structural. Daily rebalancing forces the funds to buy futures after gains and sell after losses, creating predictable mechanical flows that can press on liquidity near the close. When bitcoin is already trending, that process can reinforce the move. When bitcoin is range-bound, the same process can grind down the fund through volatility decay. Traders who understand that dynamic will use the product for defined windows, not as a long-term substitute for spot exposure. The approval therefore adds a new trading layer to the market, one that can increase intraday participation and potentially widen short-term swings.
Sentiment is likely to split between traders and longer-term holders. Traders will see a cleaner way to express sharp views with regulated access and fund-like pricing. Investors who prefer spot bitcoin or spot ether will view the product as a separate risk class, useful only for short horizons. That distinction matters because the fund's return can diverge rapidly from the underlying asset over multiple days. A bitcoin move that looks favorable in a single session can still produce a negative outcome in the 3x product if the path is choppy. The market reaction will therefore depend less on headline approval and more on how quickly the funds begin trading, how large they become, and whether their rebalancing becomes a visible force in the daily price action.
Why This Happened
The catalyst was a regulatory approval, not a change in the underlying assets. The SEC approved a Cboe BZX rule change that permits Volatility Shares to issue six ETFs targeting three times the daily return of their benchmarks. The inclusion of bitcoin and ether alongside gold, silver, crude oil and natural gas shows that the agency is now allowing a broader shelf of leveraged daily-reset products to trade on U.S. regulated exchanges. That is significant because the previous cap had limited crypto funds to two times daily leverage. The new threshold gives issuers more room to build products that match the volatility profile of digital assets, which have historically moved far more violently than traditional commodities or equities.
The macro backdrop also matters. Bitcoin and ether have become large enough, liquid enough, and structurally integrated enough into global markets to support more complex products built around them. Futures markets, options markets, and spot ETFs have already created a deep infrastructure for exposure. A 3x daily product sits on top of that infrastructure, using regulated futures rather than holding the tokens themselves. That design lowers custody risk for the fund, but it also means the product is tied to futures pricing and daily rebalancing mechanics. The approval is therefore less about changing how bitcoin is stored and more about changing how traders can express views on its price with amplified daily exposure.
The timing also reflects a broader shift in how U.S. regulators approach crypto investment products. Spot bitcoin and ether ETFs opened the door to mainstream access. Leveraged daily-reset products push the boundary further by offering a tool that is explicitly designed for trading. The approval does not signal a change in the long-term investment case for bitcoin or ether. It signals that regulators are comfortable with a wider range of product structures, provided they are built on regulated venues and clearly disclosed. For traders, that expands the menu. For issuers, it opens a new product category. For the market, it adds a flow mechanism that can interact with existing volatility in a more visible way.
Institutional and Whale Activity
Large players will likely treat these funds as a liquidity channel rather than a primary way to hold exposure. Institutional desks can already access leverage through futures, swaps, options and proprietary trading. The more interesting question is how much retail and semi-professional flow will move into the ETFs. If the funds grow quickly, their daily rebalancing can become a meaningful source of mechanical buying and selling. That flow is not directional in the way a whale’s order is directional. It is rule-based. It follows the fund’s target. It can add pressure at the close when the fund adjusts its futures positions to keep leverage pinned at 3x.
On-chain data will not directly show the fund’s holdings because the products will hold regulated futures, not actual tokens. That changes how analysts will monitor activity. Instead of watching wallet transfers or exchange inflows tied to the fund itself, market participants will track futures open interest, basis, and volume in the underlying markets. A rise in futures positioning that coincides with ETF rebalancing could show the product’s footprint. A shift in the relationship between spot and futures prices could also reveal whether the fund’s mechanical trades are moving the market. The absence of direct token holdings does not make the funds irrelevant. It simply moves the observable impact from on-chain flows to derivatives markets.
Whale behavior may also change around product launches. When new leveraged products begin trading, large traders often use the uncertainty to their advantage. They may position ahead of the first days of trading, anticipating that the funds’ rebalancing will create short-term liquidity pockets. They may also use the products as a reference point for retail flow. If the ETFs attract large inflows, whales can use that as a signal of risk appetite. If outflows appear, they can read it as fading momentum. The key point is that the funds do not create a new direction for the market. They create a new way for existing views to be expressed, and that can change the speed and shape of price discovery.
Historical Context
Leveraged daily-reset products are not new in U.S. markets. They have long existed for equities, commodities and currencies. The difference here is the underlying asset. Bitcoin and ether have a volatility profile that is far higher than most traditional benchmarks. That makes the 3x structure more powerful and more fragile. In a strong trend, the product can generate outsized gains. In a choppy market, it can lose value even if the underlying asset ends roughly flat. The historical lesson from leveraged equity and commodity funds is clear: daily reset products are designed for short-term trading, not long-term holding. The same lesson now applies to crypto.
The prior 2x cap for U.S. crypto funds gave traders a limited version of this product. The move to 3x raises the stakes. A 3x fund must rebalance more aggressively than a 2x fund, which means the mechanical flows can be larger as the fund grows. The product also becomes more sensitive to volatility decay. The math is simple. If bitcoin rises 10% one day and falls 10% the next, the underlying asset ends down 1%. A 3x fund would gain 30%, then lose 30%, ending down 9%. That is not a small difference. It is the core reason why these funds can underperform the underlying asset over multi-day periods, even when the trader’s directional call was partially right.
The historical context also includes the rapid expansion of crypto products in the U.S. Spot ETFs changed access. Options and futures deepened the market. Now leveraged daily-reset ETFs add another layer. Each layer has changed how traders interact with the asset. Spot ETFs brought passive and active investors. Options brought hedging and speculative strategies. Leveraged products bring a faster, more aggressive form of trading. The market has not stopped functioning because of these products, but the structure of participation has changed. The same is likely to happen here. The approval does not create a new bull case. It creates a new way to trade the existing bull or bear case with more intensity.
What Traders Are Watching
- Registration effectiveness: The funds cannot trade until the SEC declares the registration statement effective, and the order does not set a deadline. Traders will watch for the exact launch date and any conditions attached to the approval.
- First-day rebalancing: The initial daily reset will show how much mechanical flow the fund can generate. A large first-day move could reveal whether the product becomes a visible force in the market.
- Futures open interest and basis: Because the funds hold regulated futures, traders will monitor open interest, funding, and basis to understand where the product is taking exposure and whether it is affecting derivatives pricing.
- Volatility decay: In choppy markets, the 3x structure can lose value quickly. Traders will watch for periods where bitcoin and ether move in tight ranges, because that is when the product is most likely to underperform the underlying asset.
- AUM growth: The bigger the fund becomes, the larger its rebalancing impact. A rapid rise in assets under management could turn the product into a meaningful source of daily flow, while modest growth would limit its market effect.
Disclaimer: This article is provided for informational and educational purposes only and does not constitute financial, investment, or trading advice. Digital assets carry significant market risk.
Comments
You must be logged in to post a comment.
Login or Register