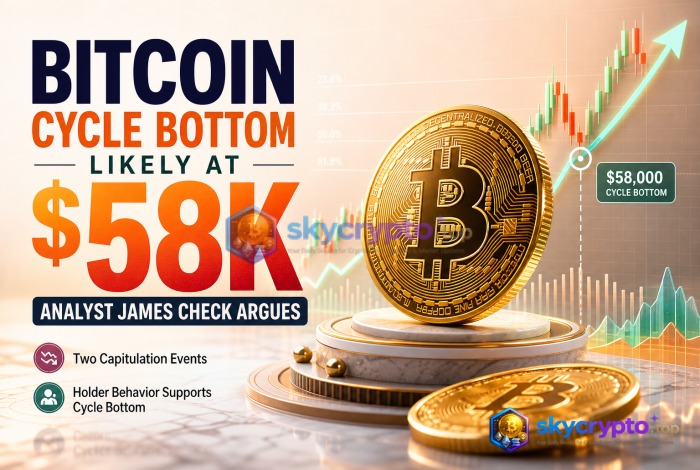
On-chain analyst James Check believes Bitcoin established its cycle bottom near $58,000 after two distinct capitulation events, challenging widespread expectations of a lower low in October 2026. The Checkonchain founder argues that holder behavior shifts and cost-basis concentration between $58,000 and $70,000 signal selling exhaustion arrived months ahead of the calendar-driven forecast. Grayscale research head Zach Pandl independently reached the same conclusion, stating prices likely bottomed at the end of June.
- James Check identifies two capitulation events — a February "price-pain" drop toward $60,000 and a June-July "time-pain" grind near $58,000 — as evidence the cycle bottom is in.
- Approximately $300 billion in Bitcoin cost basis sits between $58,000 and $70,000, with 4 million BTC moving from unrealized loss to profit during the recovery.
- Long-term holders now control roughly 80% of Bitcoin wealth, reducing near-term sell pressure after a short-term rebound.
- Check rejects the four-year cycle as a mechanical timing tool, urging traders to watch cost basis, realized losses, and accumulation patterns instead of calendar dates.
- Grayscale's Zach Pandl corroborates the $58,000 bottom call, adding institutional weight to the on-chain thesis.
Market Reaction
Bitcoin traded around $77,400 at the time of Check's interview, nearly 39% below the October 2025 peak just above $126,000. The partial recovery from the $58,000 low has been marked by choppy, range-bound action rather than a sharp V-shaped reversal. Volume profiles on major exchanges show declining sell-side pressure on dips toward $60,000, while futures open interest has failed to regain its April highs, suggesting leveraged speculators remain cautious. Funding rates across perpetual swap markets have hovered near neutral or slightly negative, a sign that aggressive longs are not piling in despite the bounce. Traders who anchored to the four-year cycle narrative — expecting a fourth-quarter 2026 bottom — have been forced to reassess positioning as each week passes without a new low.
Sentiment indicators paint a mixed picture. The Crypto Fear & Greed Index has oscillated between "Fear" and "Neutral" for weeks, refusing to flip decisively to "Greed" even as price holds above $70,000. Social media engagement metrics for Bitcoin-related content remain depressed compared to the November 2025 euphoria phase. However, options market skew shows put premiums elevated relative to calls, indicating professional desks are still pricing in tail risk. This divergence — spot holders reluctant to sell, derivatives players hedging downside — creates a coiled spring that often precedes a directional breakout. The next catalyst, whether macro or flow-driven, will likely resolve this tension violently.
Why This Happened
Check's framework distinguishes between two capitulation mechanisms. The February decline toward $60,000 represented "price-pain capitulation" — investors who bought near the $126,000 peak sold at substantial realized losses, crystallizing pain quickly. The June-July grind near $58,000 was different: a "time-pain capitulation" where months of sideways action eroded conviction, forcing holders to question whether recovery was possible at all. The six-month gap between these events, Check emphasizes, is the critical variable. Time, not price magnitude, broke the marginal seller. This aligns with on-chain data showing realized loss volumes spiked in February but remained elevated through the summer, a pattern consistent with a two-phase washout.
Macro backdrop matters. The Federal Reserve held rates restrictive through the first half of 2026, with the dollar index (DXY) trading above 105 for much of the period. Risk assets globally faced headwinds from sticky services inflation and resilient labor markets. Bitcoin's correlation with the Nasdaq 100 remained above 0.7 on a 30-day rolling basis, meaning equity drawdowns transmitted directly to crypto. Yet the $58,000 level held despite the S&P 500 testing correction territory in April. That resilience, Check argues, reflects absorption: the marginal seller was exhausted, and the marginal buyer — long-term accumulators — stepped in. The cost-basis cluster between $58,000 and $70,000, representing roughly $300 billion in aggregate acquisition value, became a magnetic zone where supply dried up.
Institutional and Whale Activity
On-chain analytics reveal a structural shift in holder composition. Entities classified as long-term holders (coins unmoved for 155+ days) now control approximately 80% of the circulating supply, up from roughly 65% at the October 2025 peak. This cohort has shown minimal distribution during the recovery from $58,000 to $77,000, with net position changes flat to slightly positive. Meanwhile, short-term holder supply has contracted, suggesting weak hands were flushed during the capitulation windows. Whale wallets (1,000+ BTC) accumulated an estimated 120,000 BTC between March and August, per Glassnode cluster data, with notable inflows to custody addresses linked to known institutional custodians.
Futures markets tell a complementary story. CME Bitcoin futures open interest peaked in March 2026 and has declined 22% since, even as price recovered. This divergence suggests leveraged speculators reduced exposure while spot-driven buyers absorbed supply. The basis trade — long spot, short futures — has narrowed to annualized yields below 8%, down from 15%+ in January, reducing carry-driven demand for synthetic short exposure. ETF flow data shows U.S. spot Bitcoin ETFs recorded net inflows in five of the last eight weeks through August, totaling roughly 45,000 BTC. However, pace has slowed from the March peak, consistent with Check's observation that the easiest accumulation occurred during the capitulation phase. The next wave of institutional allocation likely awaits regulatory clarity on custody rules and a decisive break above $85,000.
Historical Context
Bitcoin's four-year cycle narrative, anchored to halving events, has correctly identified approximate bottom windows in 2011, 2015, 2019, and 2022. Each cycle bottom occurred 12-18 months post-halving, with the 2022 low forming in November — 17 months after the May 2020 halving. The current cycle's halving occurred in April 2024, placing a calendar-projected bottom between April and October 2026. Check's $58,000 call in June-July 2026 would front-run this window by 3-15 months. Precedent exists: the 2015 bottom formed in January, 13 months post-halving, while 2019 bottomed in December, 18 months post-halving. Timing variance is the rule, not the exception.
What distinguishes this cycle is the scale of institutional participation and the presence of spot ETFs, which did not exist in prior cycles. The 2022 bear market bottom coincided with the FTX collapse — an idiosyncratic credit event — rather than pure cycle timing. In 2018-2019, the bottom formed after a 12-month grind from $6,000 to $3,200 and back, a classic time-pain capitulation. Check's argument rhymes with that pattern: price pain came first (February), then time pain (June-July). The difference is speed. Information flows faster, capital moves faster, and the participant base is more sophisticated. Expecting a mechanical repeat of 2022's November low ignores the structural changes in market microstructure. The calendar is a map of past terrain; the territory has shifted.
What Traders Are Watching
- $78,500-$80,000 resistance cluster: The 200-day moving average converges with the 0.5 Fibonacci retracement of the $126K-$58K decline. A weekly close above $80,000 would confirm the bottom thesis and trigger trend-following flows.
- $72,000-$73,000 support zone: Prior resistance from the March-April range, now flipped to support. Holds here maintain the higher-low structure; a break risks retest of $65,000.
- Realized cap HODL waves: Watch for the 6-month+ holder band to stabilize above 60% of realized cap, signaling long-term conviction is not rotating into distribution.
- CME futures basis annualized yield: A sustained move above 10% would indicate renewed leveraged long appetite; a drop below 5% signals carry trade unwind risk.
- U.S. macro calendar — September FOMC and October CPI: A dovish pivot or soft inflation print could provide the macro tailwind for a breakout; sticky data extends the range.
Disclaimer: This article is provided for informational and educational purposes only and does not constitute financial, investment, or trading advice. Digital assets carry significant market risk.
Comments
You must be logged in to post a comment.
Login or Register