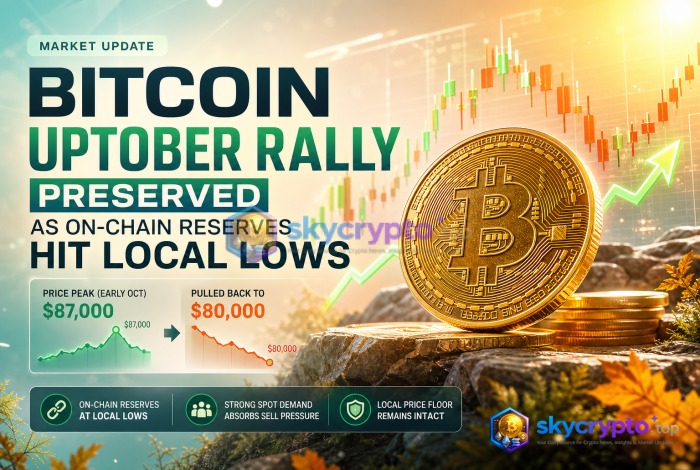
Bitcoin established a firm local price floor in early October as persistent spot demand successfully absorbed severe macroeconomic headwinds and geopolitical turbulence. Despite a sharp pullback from an early-month peak of $87,000 down to near $80,000 on October 8, critical structural indicators indicate that the broader seasonal rally remains intact. Active supply contraction across centralized trading platforms and unwavering accumulation by large-scale capital allocators demonstrate that market participants view current valuations as an attractive accumulation zone rather than a point of structural breakdown.
- On-chain supply on exchanges dropped 1.7% from 2.726 million to 2.68 million BTC since late September, signaling reduced sell-side liquidity.
- Whale cohorts holding over 3 million BTC absorbed the price drop to $80,000 without liquidating holdings.
- Macro headwinds, including 24-year high U.S. bond yields, are counterbalanced by expectations of cooling Federal Reserve rate hike paths into 2027.
Market Reaction
Market reaction across major digital asset exchanges highlighted a rapid transition from speculative leverage flushing to strong spot-driven defense over the past fortnight. When Bitcoin advanced toward $87,000 on October 2, derivative markets exhibited elevated open interest and rising funding rates, leaving market structure vulnerable to short-term downside shocks. The subsequent retracement down to $80,000 on October 8 effectively wiped out over-leveraged long positions, resetting perpetual futures funding rates back to neutral levels and clearing excess speculative debt from the system.
Rather than triggering secondary waves of panic selling, the drop toward $80,000 uncovered thick layers of order book bid depth. Institutional trading desks and high-net-worth buyers stepped into the market aggressively as price action neared key technical support levels. Spot volume profiles recorded a distinct uptick in buy-side absorption during the lowest prints of the move, indicating that physical demand for the asset remains strong despite short-term derivatives instability.
Traders shifted from initial panic to strategic position-building as price action stabilized above $80,000. Option markets reflected this sentiment shift through a flattening volatility skew, showing reduced demand for downside put protection and increased interest in upside call spreads targeting the final quarter of the year. This transition from leverage liquidation to spot accumulation underscores a market that is absorbing sell-side liquidity with remarkable efficiency.
Why This Happened
Understanding the catalyst behind this recent market cycle requires examining a complex matrix of macroeconomic pressures that weighed heavily on global risk assets. U.S. Treasury yields spiked to 24-year highs across benchmark tenors, raising the risk-free rate of return and imposing severe valuation pressure on non-yielding assets worldwide. Concurrently, rising global crude oil prices reintroduced headline inflation risks, forcing fixed-income markets to reprice expectations regarding long-term central bank monetary policy stances.
These broader macroeconomic tightening conditions coincided with a temporary deceleration of capital inflows into spot exchange-traded products. After months of consistent net positive creations, institutional flows slowed during the first week of October, removing an important source of daily market liquidity. The convergence of elevated sovereign bond yields, energy market volatility, and moderating institutional fund creation created a challenging short-term backdrop that triggered the price correction from $87,000.
However, structural counter-currents began emerging beneath the surface to mitigate these pressures. Expectations surrounding future Federal Reserve policy trajectories shifted, with financial markets pricing in a definitive cooling of interest-rate hike expectations extending into 2027. In tandem, market participants anticipate reduced political uncertainty following the conclusion of the upcoming U.S. midterm elections, providing institutional asset managers with greater clarity to re-evaluate strategic capital allocations across risk-on asset classes.
Institutional and Whale Activity
On-chain metrics reveal that market participants operating on larger timeframes remained completely unfazed by the pullbacks in spot prices. Wallet cohorts holding 1,000 BTC or more—commonly referred to as whales—maintained an aggregate balance exceeding 3 million BTC throughout the entire price drop from $87,000 to $80,000. Rather than liquidating positions or hedging spot exposure on derivatives venues, these large-scale capital allocators continued building structural positions, treating the lower price range as a strategic liquidity window.
Simultaneously, aggregate Bitcoin inventories across centralized exchanges experienced a sustained contraction. Total BTC supply held on exchange order books decreased from 2.726 million BTC on September 20 down to 2.68 million BTC by mid-October, representing a clear 1.7% reduction in liquid market supply. Although minor temporary spikes in exchange deposits occurred during the initial drop to $80,000, the macro trend of net exchange outflows resumed almost immediately, removing physical coins from circulating availability.
This persistent drain of exchange liquidity points directly toward cold storage migration and private over-the-counter settlement activity. High-conviction investors and corporate treasuries continue transferring spot assets into non-custodial storage solutions, reducing the total supply immediately accessible to sell-side pressure. As liquid inventory contracts on public order books while whale wallet balances remain elevated above historical benchmarks, the structural setup for a supply-driven price expansion continues to strengthen.
Historical Context
The historical behavior of Bitcoin during the month of October provides essential context for interpreting current market dynamics. Historically, October has earned a reputation for generating positive overall returns, often dubbed "Uptober" across global trading desks. However, past performance data shows that these strong monthly outcomes rarely unfold in a linear fashion; prior cycles frequently featured sharp early-month sell-offs designed to shake out weak speculative positioning before establishing a durable launchpad for Q4 expansion.
Comparing present conditions to previous market cycles reveals structural parallels to previous post-halving transition phases. During prior expansion cycles, price consolidation periods accompanied by declining exchange reserves consistently signaled underlying market strength. When liquid supply on exchanges drains while long-term holders absorb sell-side inventory, market structure becomes highly sensitive to positive shifts in net buying demand, often leading to rapid upward price adjustments once consolidation concludes.
Additionally, the retention of structural support near $80,000 aligns closely with key historical cost-basis bands and moving averages observed during prior bull market continuations. The ability of spot buyers to defend these specific technical thresholds amid extreme macroeconomic headwinds mirrors structural bottoming patterns documented in previous cycles, reinforcing the perspective that current market action represents a routine mid-trend consolidation rather than a systemic trend reversal.
What Traders Are Watching
Market participants are closely tracking several pivotal technical levels, liquidity indicators, and fundamental catalysts to determine whether the recent local bottom will successfully translate into a full-scale Q4 expansion.
- $87,000 Overhead Resistance: A decisive daily and weekly close above the October local high of $87,000 is required to confirm a complete technical breakout and clear the path toward test of key historical highs.
- $80,000 Key Demand Floor: Maintaining structural integrity above the $80,000 psychological and technical support band remains essential to preserve the structural floor established during the early-October drawdown.
- Exchange Inventory Velocity: Analysts are watching whether total exchange reserves continue breaking below the 2.68 million BTC mark or if unexpected deposit spikes signal renewed sell-side pressure from large holders.
- U.S. Treasury Yield Trajectory: Institutional desks are monitoring benchmark U.S. 10-year Treasury yields for signs of stabilization or retreat from 24-year highs, which would act as a major macroeconomic tailwind for risk assets.
- Whale Balance Accumulation Rate: Tracking whether the total balance held by entities owning more than 1,000 BTC continues expanding above the current 3 million BTC threshold as spot prices consolidate.
As supply metrics contract and long-term capital allocators continue absorbing spot inventory, market attention remains fixed on macro liquidity shifts and institutional fund flows. Should macroeconomic pressures ease in tandem with reduced political uncertainty, the structural foundation established around current price levels appears well-positioned to validate the broader Q4 seasonal expansion thesis.
Disclaimer: This article is provided for informational and educational purposes only and does not constitute financial, investment, or trading advice. Digital assets carry significant market risk.
Comments
You must be logged in to post a comment.
Login or Register